After an accident, the moment many victims dread arrives: the insurance company presents a reasoned offer. This seemingly technical document is filled with legal references and figures that appear unchangeable. But the truth is, it 's possible to challenge the insurance company's reasoned offer , and doing so effectively can mean thousands of euros in your compensation. In this article, we explain how this process works, what arguments you can use, and why having specialized legal advice is crucial.
What is the insurer's motivated offer?
A reasoned offer is the formal proposal that an insurance company is legally obligated to present to victims of traffic accidents when there is clear liability. It is regulated by the Law on Civil Liability and Insurance in Motor Vehicle Traffic and must be submitted within a maximum of three months from the date of the accident.
This offer must include:
- The total amount that the insurer proposes to pay as compensation.
- The criteria used to calculate that amount (medical assessment, days off work, after-effects, etc.).
- The legal basis on which the calculation is based.
The problem is that, although the offer must be "justified", the valuation criteria usually benefit the insurer and do not always reflect the actual damage suffered by the victim.
Why motivated offers are almost never enough
Insurance companies are businesses with legal and medical teams that work to minimize payouts. When calculating compensation, they typically use conservative assessments of injuries, their own medical evaluations that underestimate the long-term effects, and interpretations of the compensation scale that are most favorable to them.
This means that, in most cases, the initial offer is lower than what is truly warranted. In cases of serious injury, the difference between accepting the first offer and pursuing legal action can be enormous. You can read more about complex situations of this kind in the case of Raúl, a serious accident that continues to generate debate , which perfectly illustrates how the initial valuation may not reflect the actual damage.
How to refute a motivated offer step by step
1. Don't sign anything without reading it carefully.
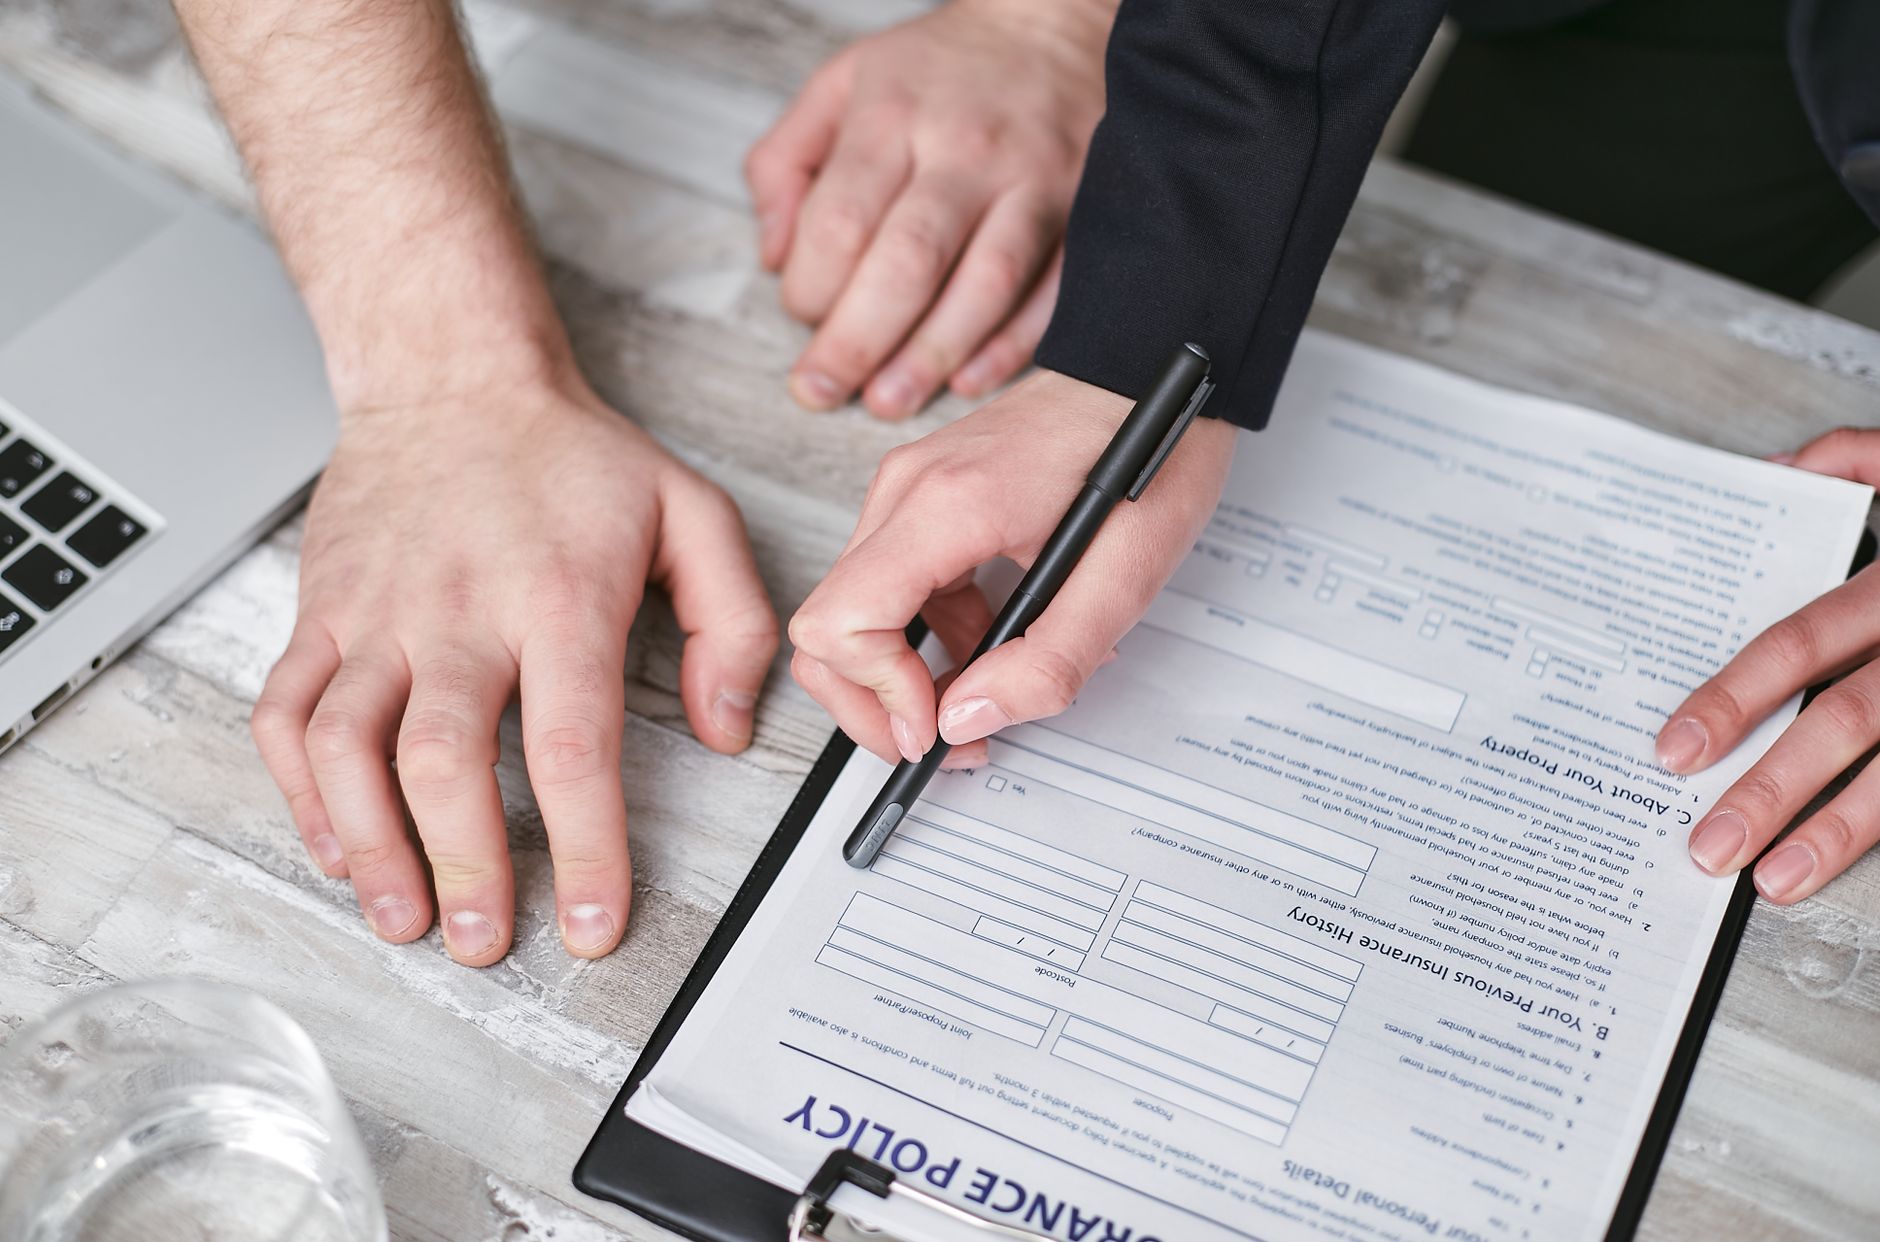
The first mistake is the most common: signing the acceptance document without understanding what it entails. By signing, in many cases you are waiving any future claims. Although the insurance company may present the signature as a simple formality, it has irreversible legal consequences.
2. Request all medical documentation
To refute the offer, you need to thoroughly document the damage you suffered. Gather all medical reports, diagnostic test results, sick leave and return-to-work forms, rehabilitation reports, and any other documents that prove the impact of the injuries on your daily and professional life.
3. Request an independent medical evaluation
A report from a medical examiner or an independent medical expert is one of the most powerful tools for challenging the offer. A neutral expert can identify consequences that the insurer's valuation has ignored or underestimated, such as chronic neck injuries, psychological damage, functional limitations, or disfigurement.
4. Review the applied scale
Since 2016, compensation for traffic accidents in Spain has been calculated according to the scale of the System for the Assessment of Damages and Losses Caused to Persons in Traffic Accidents . This scale distinguishes between bodily injury, basic personal injury, specific injury, and property damage.
The insurance company may be applying the compensation scale incompletely, failing to recognize certain specific damages to which you are entitled, or incorrectly calculating lost earnings (what you have lost due to your injuries). A specialized lawyer can review each point to ensure the scale is being applied correctly.
5. Submit a written and reasoned response
Once you have the independent medical report and the revised compensation scale, you can formally respond to the insurer's offer. This response must be in writing, detailing each point of the discrepancies and presenting your counterproposal for compensation with the legal and medical basis that supports it.
This phase is crucial: a well-argued response can lead the insurer to voluntarily improve its offer without the need to go to court.
6. If there is no agreement, go to court without fear.
If negotiations fail, the next step is legal action. Many victims avoid this option due to fear of the costs or the uncertainty, but in practice, courts often award compensation far exceeding the initial offers from insurance companies when the case is well-documented.
Furthermore, if the judgment exceeds the reasoned offer, the insurer may be ordered to pay default interest from the date of the accident, which significantly increases the final compensation.
Common mistakes to avoid
Besides signing hastily, there are other common mistakes that can weaken your position:
- Failure to attend all medical appointments: Periods without medical assistance may be interpreted as full recovery and reduce compensation.
- Post on social networks: Photographs or comments that contradict the severity of the injuries can be used against you.
- Negotiating without legal advice: Insurance companies have teams of lawyers. Negotiating alone is a clear disadvantage.
- Letting deadlines pass: The statute of limitations applies to claims for personal injury, so acting quickly is crucial.
The role of the accident lawyer
Having a specialized lawyer isn't a luxury; it's an investment that almost always pays off. Lawyers' fees in these cases are usually agreed upon on a contingency basis (a percentage of the settlement), meaning they only get paid if they manage to improve your situation.
A good lawyer not only knows the fee schedule inside and out, but also knows how to obtain evidence, how to select trustworthy medical experts, and how to negotiate with insurance companies from a position of strength. If you'd like to learn more about the work we do, you can visit our About Us section or explore our legal blog, which features articles on various areas of law.
In the area of collective claims and the defense of rights, technical rigor also makes the difference. This is demonstrated, for example, by the work carried out in the APIGF claim , where documentation and legal strategy were decisive.
One last piece of advice before making any decisions
If you've just received a motivated offer, do one thing before anything else: consult with a specialized lawyer. Most offer a free or no-obligation initial consultation. In that first meeting, you can find out if the offer is reasonable, if your injuries have been properly assessed, and what your realistic options are.
Don't let urgency or pressure from the insurance company lead you to make a hasty decision. The time you invest in getting informed and surrounding yourself with the right professionals can translate into fair compensation that truly covers the damage you've suffered. And that, when we're talking about injuries that affect your health, your work, and your quality of life, is priceless.
